Quantum Financial Architectures: Transcending Classical Optimization Limits
-
 Omar Al-Hassan
- 12 Sep, 2026 20:36
The Quantum Frontier of High-Frequency Capital Markets
The landscape of quantitative finance has long been dominated by the ghost of classical optimization. From Black-Scholes derivatives to Monte Carlo simulations, our current financial infrastructure is tethered to the computational limits of von Neumann architectures. However, we are currently witnessing a seismic shift. The convergence of fault-tolerant quantum error correction and multimodal visual intelligence—exemplified by architectures like SenseNova-U1.5—is beginning to offer a glimpse into a future where market efficiency is no longer bounded by linear probability density functions.
As we scale towards practical quantum advantage, the challenge lies not in raw qubit count, but in the coherence of our error-correction protocols. Financial models require absolute fidelity; a bit-flip in a high-frequency trading algorithm or a corrupted data block in risk assessment could trigger catastrophic market instability. This is where the mathematical rigor of Rényi coherent information becomes paramount. By moving beyond classical Shannon entropy and embracing the hierarchy of Rényi indices, we can construct robust, fault-tolerant pipelines that ensure our quantum financial models remain stable even in the presence of stochastic Pauli noise. We are entering an era where capital allocation is driven by topological data analysis and quantum-native reasoning, transcending the binary constraints of the past.
 ]
Error Correction and the Reliability of Financial Data
In the realm of quantum-enhanced financial modeling, the integrity of the data stream is the primary obstacle to widespread adoption. Classical financial data is often noisy, incomplete, and highly asynchronous. When we map these parameters onto quantum states, we encounter Pauli noise generated by independent Bernoulli events—common in volatile market indicators. The recent advancements in stabilizer codes provide a robust framework for handling this.
The core insight from recent developments in Rényi coherent information is that we no longer need to rely exclusively on von Neumann entropy. For stabilizer codes, the Rényi-$n$ coherent information acts as a powerful, computable proxy. Because this metric is nondecreasing in $n$ for independent Pauli noise, it provides a stable threshold for quantum error correction. In practice, this means we can establish a hierarchy of reliability. When our quantum circuits execute financial forecasting tasks, we can utilize syndrome-conditioned recovery to filter out stochastic noise before it propagates into the decision-making layer of our portfolios.
Consider the following implementation of a stabilizer-check simulator in Python, designed to evaluate the robustness of a state preparation against bit-flip errors.
import numpy as np

class StabilizerFinancialModel:
    """
    A foundational class to simulate stabilizer error correction
    for quantum financial volatility forecasting.
    """
    def __init__(self, n_qubits):
        self.n_qubits = n_qubits
        self.syndromes = np.zeros(n_qubits)

    def measure_syndrome(self, state, noise_model):
        # Simulate Pauli noise effect on the syndrome-logical class
        noise = np.random.binomial(1, noise_model, self.n_qubits)
        self.syndromes = (self.syndromes + noise) % 2
        return self.syndromes

    def calculate_renyi_proxy(self, syndrome_bits, index=2):
        # Calculating Rényi entropy difference H_n(C) - H_n(T)
        # Simplified proxy for coherent information saturation
        entropy_c = -np.sum((syndrome_bits / np.sum(syndrome_bits)) * np.log2(syndrome_bits / np.sum(syndrome_bits)))
        return entropy_c

# Implementation of the syndrome check
model = StabilizerFinancialModel(n_qubits=128)
current_syndrome = model.measure_syndrome(state=None, noise_model=0.05)
print(f"Rényi-proxy coherence level: {model.calculate_renyi_proxy(current_syndrome)}")
Multimodal Synergy in Financial Intelligence
While quantum circuits handle the mathematical optimization of portfolios, the interpretation of unstructured financial data—news feeds, infographic market reports, and global visual trends—requires a different breed of intelligence. This is where models like SenseNova-U1.5 redefine the paradigm. By moving toward a native unified multimodal framework, we eliminate the reliance on VAEs or encoder-heavy architectures that often degrade visual fidelity in complex financial infographics.
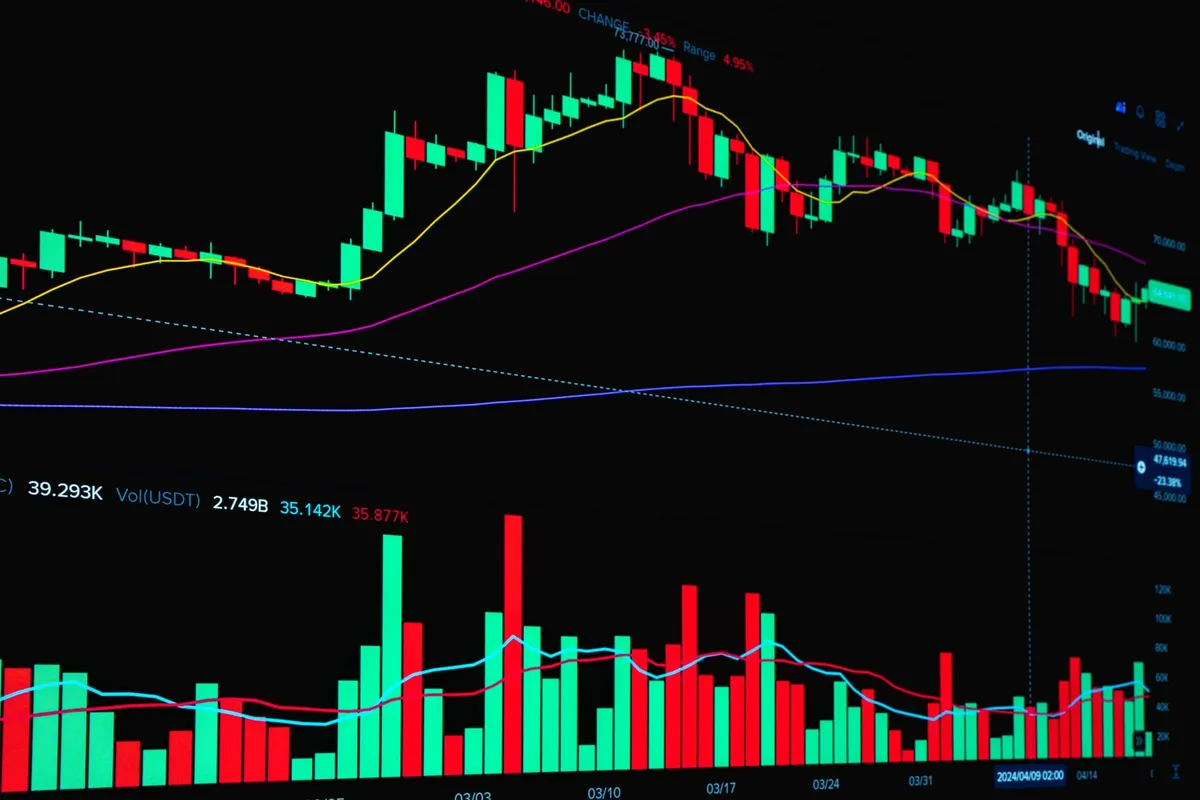
The capability of these models to perform spatially coherent patch reconstruction is not merely a benchmark for image generation; it is a breakthrough for interpreting financial charts, multi-page technical audits, and complex asset-class interdependencies. When we integrate this visual reasoning with quantum optimization, we create an end-to-end system where the “visual” state of the market (e.g., chart patterns, global supply chain bottlenecks visualized via infographics) is fed directly into the quantum processor as a series of structured parameters. The model’s ability to handle high-resolution visual input (up to 4K) allows us to detect subtle trend reversals that are invisible to classical OCR-based analysis.
Scaling Financial Optimization via On-Policy Distillation
The training of financial AI requires specialized experts. A standard large language model often misses the nuances of volatility modeling or the specific requirements of regulatory compliance in financial reporting. By utilizing multi-expert on-policy distillation, we can distill the intelligence of a massive MoT (Mixture-of-Tokens) architecture into a specialized financial reasoning agent.
In a production environment, this translates to deployment patterns that rely on specialized infrastructure. We must consider how these models scale within a Kubernetes environment, where GPU-intensive visual processing meets the latency requirements of financial feedback loops. The following configuration demonstrates a production-grade deployment for a multimodal inference service that could theoretically serve as the intake layer for our quantum optimizer.
apiVersion: apps/v1
kind: Deployment
metadata:
  name: financial-vision-engine
spec:
  replicas: 3
  selector:
    matchLabels:
      app: sense-nova-fin
  template:
    metadata:
      labels:
        app: sense-nova-fin
    spec:
      containers:
      - name: multimodal-inference
        image: sense-nova-u1.5:latest
        resources:
          limits:
            nvidia.com/gpu: 4
            memory: "64Gi"
        env:
        - name: REINFORCEMENT_LEARNING_MODE
          value: "on-policy"
        - name: EXPERT_AESTHETICS_WEIGHT
          value: "0.85"
Topological Stability and Market Asymptotics
One of the most profound intersections between physics and finance is the concept of saturation in coherent information. In the context of the arXiv research on stabilizer codes, the saturation of Rényi coherent information is proven to be equivalent to asymptotically perfect recovery. In financial terms, this implies a “limit of information” where our ability to hedge against risk becomes theoretically perfect—given, of course, that our quantum noise is controlled.
When we model market portfolios as stabilizer codes, the “logical classes” correspond to our high-level asset strategies, and the “syndromes” are the real-time adjustments required by market fluctuations. As our models increase in complexity (the Rényi index $n$), we essentially refine our ability to filter out market noise. This is not just a mathematical curiosity; it is a roadmap for building the next generation of algorithmic trading platforms that can survive “black swan” events by treating them as syndrome anomalies rather than unforeseen disruptions. By applying the postselection technique mentioned in recent research—matching syndromes between one data block and $n-1$ auxiliary blocks—we can effectively “post-select” the most stable market states for our algorithmic execution, ignoring segments of the market that exhibit high-entropy, low-predictability characteristics.
 ]
Synthesis of Quantum and AI Paradigms
The future of fintech is not binary; it is a blend of probabilistic quantum error-correction and high-dimensional AI reasoning. We are transitioning away from systems that “guess” the market towards systems that “observe and compute” the market with physical precision.
The integration of SenseNova-U1.5’s visual reasoning allows us to ingest market data at a scale previously reserved for human perception, while the quantum stabilizer protocols ensure that our subsequent optimization steps are mathematically sound and resistant to the stochastic noise inherent in real-world trading environments. This is a multi-disciplinary challenge that requires deep knowledge of both the underlying Hilbert space physics and the high-level architecture of distributed AI systems. As we move forward, the competitive advantage in the global financial market will belong to those who can bridge this gap—the developers and quants who can translate abstract Rényi-index proofs into scalable, containerized, and fault-tolerant software. We are no longer limited by the noise of the classical world; we are constructing a bridge to a deterministic, high-fidelity future.
The Path Toward Quantum-Financial Sovereignty
We have navigated the technical complexities of stabilizer codes and the multimodal advancements in visual intelligence to arrive at a powerful synthesis. The hierarchy of Rényi information is more than a theoretical tool; it is the cornerstone of our future error-correction strategies in financial modeling. By utilizing the nondecreasing nature of Rényi coherent information, we ensure that our risk assessment protocols are not only accurate but inherently stable against the chaotic variables of the global economy.
Simultaneously, by adopting end-to-end architectures like SenseNova-U1.5, we remove the “black box” nature of classical AI systems, enabling a higher degree of interpretability and instruction-following that is essential for regulated financial environments. The code blocks provided demonstrate the practical application of these theoretical breakthroughs—from simulating quantum syndromes to deploying specialized multimodal agents in a production environment.
The convergence of these technologies signifies the end of the “classical approximation” era. We are moving toward a period of high-precision financial engineering where the mathematical certainty of quantum mechanics meets the cognitive flexibility of multimodal AI. The architects of this future will be those who master both the physics of information and the engineering of intelligence. The infrastructure is being built today; the markets of tomorrow await the results of this synthesis.
#QuantumComputing #FinancialModeling #AI #RényiEntropy #FinTech #StabilizerCodes #HighPerformanceComputing